An Indonesian Perspective: A Ground Reality
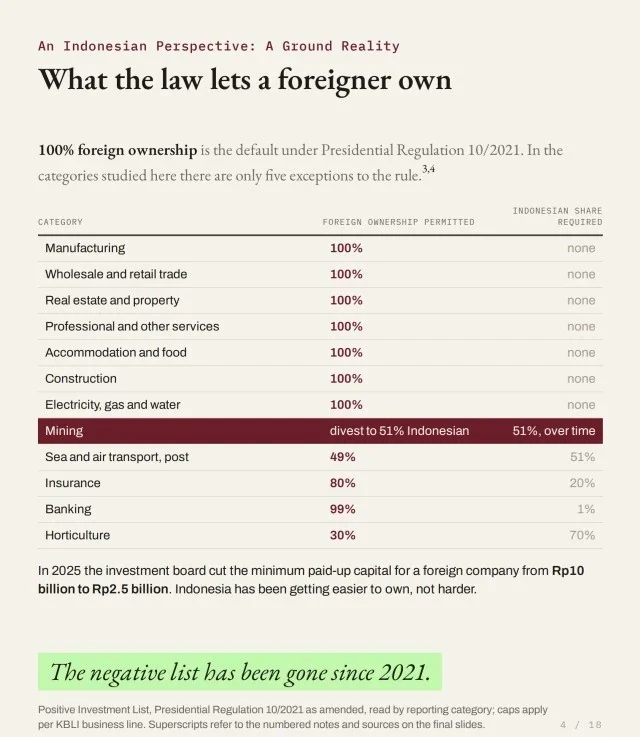
In the categories where a foreigner may legally own the lot, 67% took a local partner anyway.
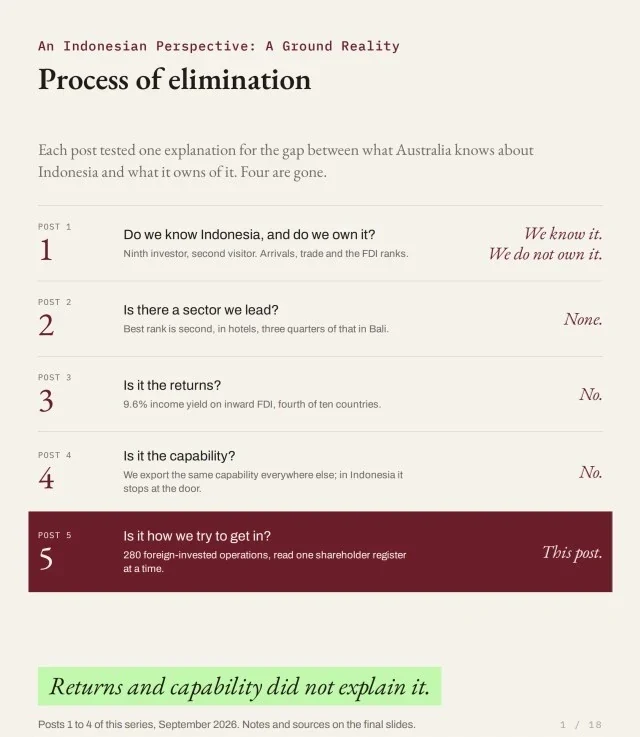
Four posts ago, after a meeting with Dr. Sandiaga S. Uno, I arrived at the following conclusion: Australians know Indonesia better than almost any foreign market, and own less of it than almost any foreign investor.
Returns did not explain it. Capability did not explain it.
That leaves how we try to get in.
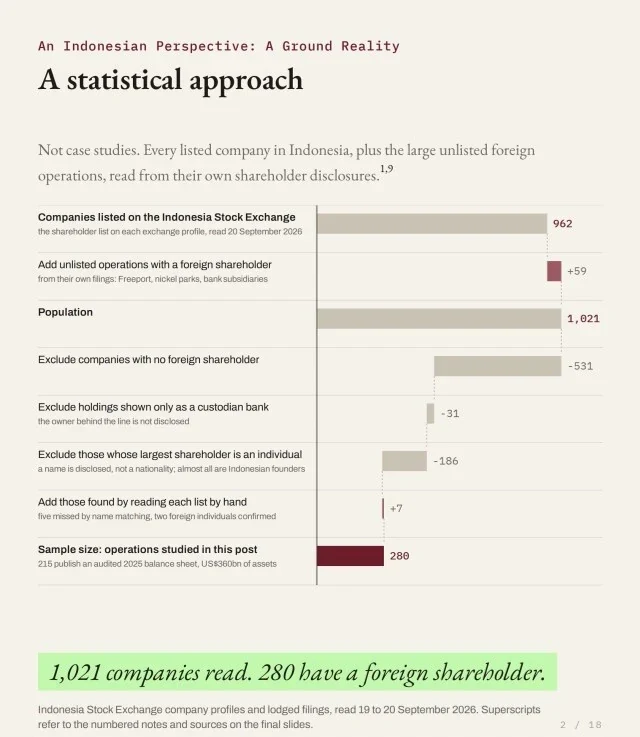
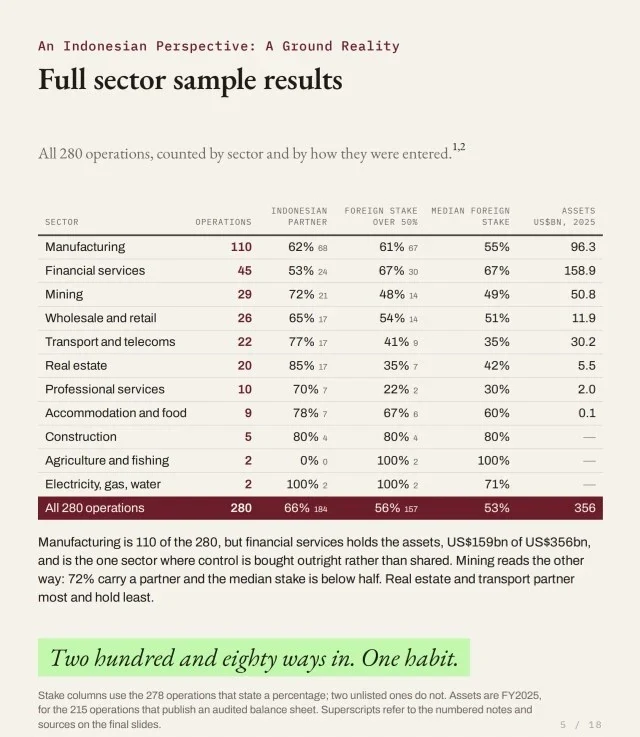
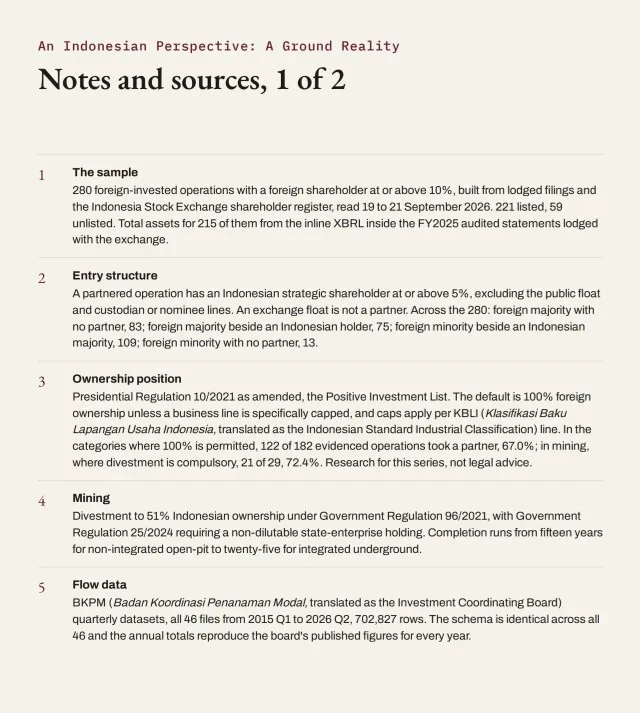
So I decided to use a statistical approach to understand the ground reality. Every company listed in Jakarta, plus the large unlisted foreign operations: 1,021 businesses, of which 280 have a foreign shareholder at or above 10%. That is the sample.
First, what the law allows. Presidential Regulation 10/2021 replaced the old negative list with a positive one, and the default became 100% foreign ownership unless a specific line is capped. Manufacturing, construction, telecoms, electricity, retail, property and hospitality are all open.
Now the finding.
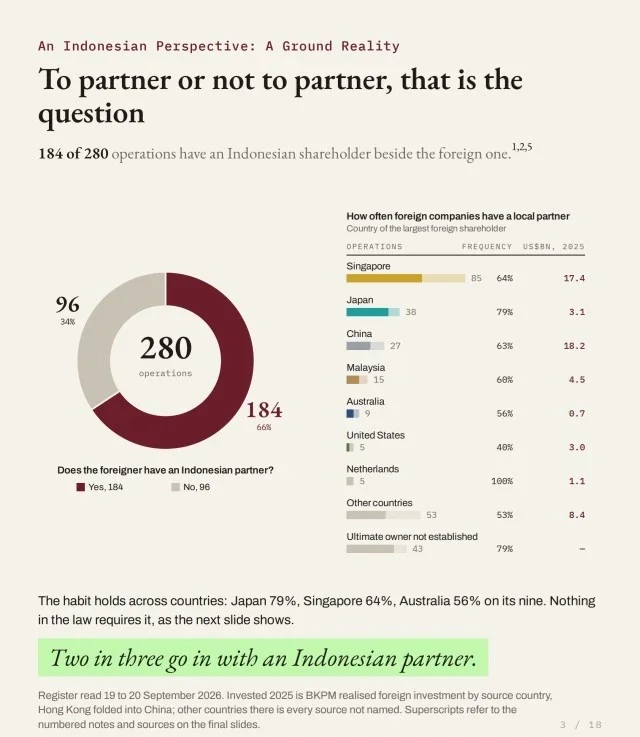
184 of the 280 carry an Indonesian strategic shareholder. That's 66%.
In the categories where a foreigner may legally own the lot, 67% took a local partner anyway.
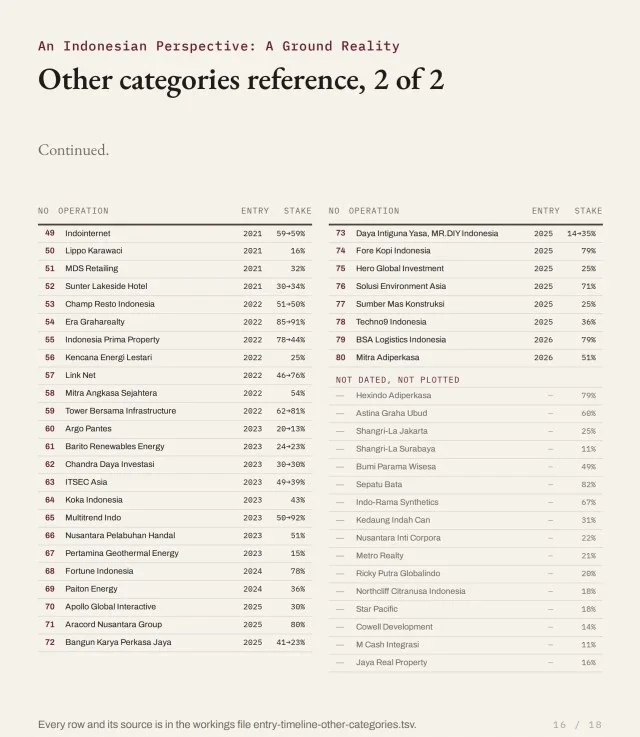
Then we dated 240 of the entries from the investors' own releases and filings, showing when each holder came in and every change since. Three patterns:
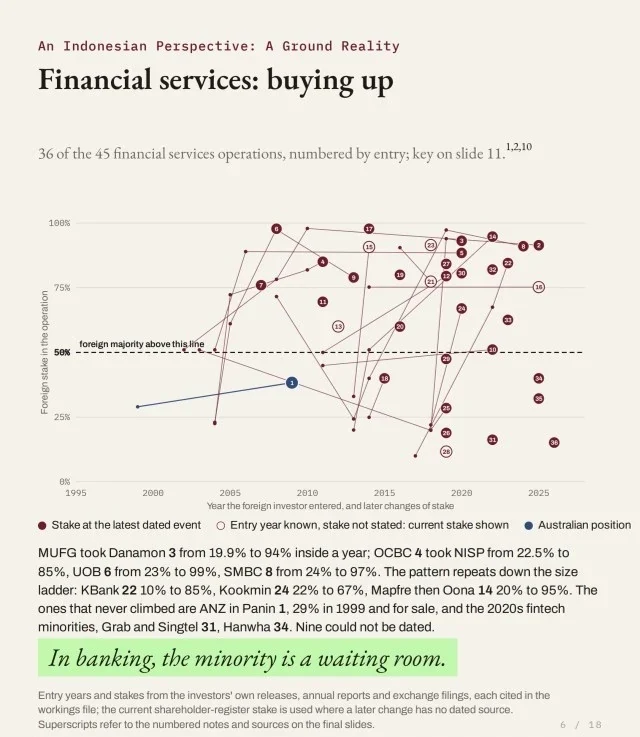
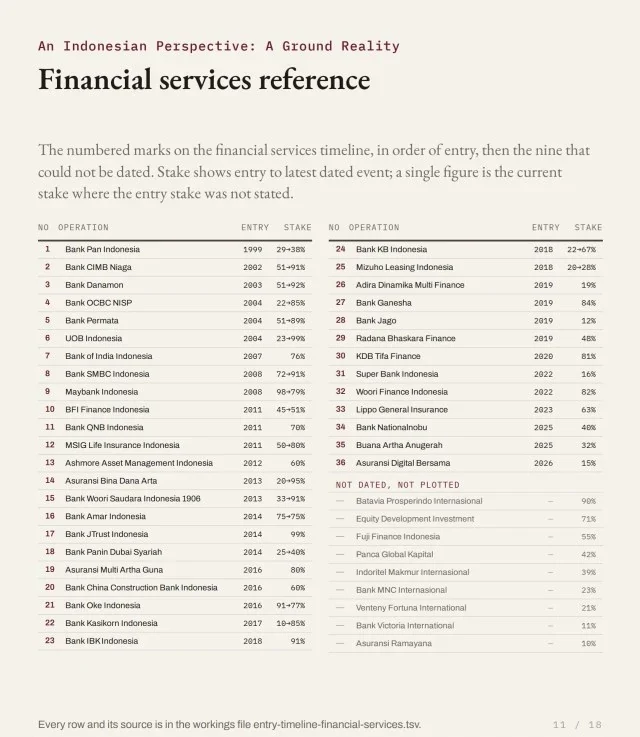
- Banking buys in and then buys up. MUFG took Danamon from 19.9% to 94% inside a year. Kasikorn went 10% to 85%, Kookmin 22% to 67%. In banking, a minority is a waiting room.
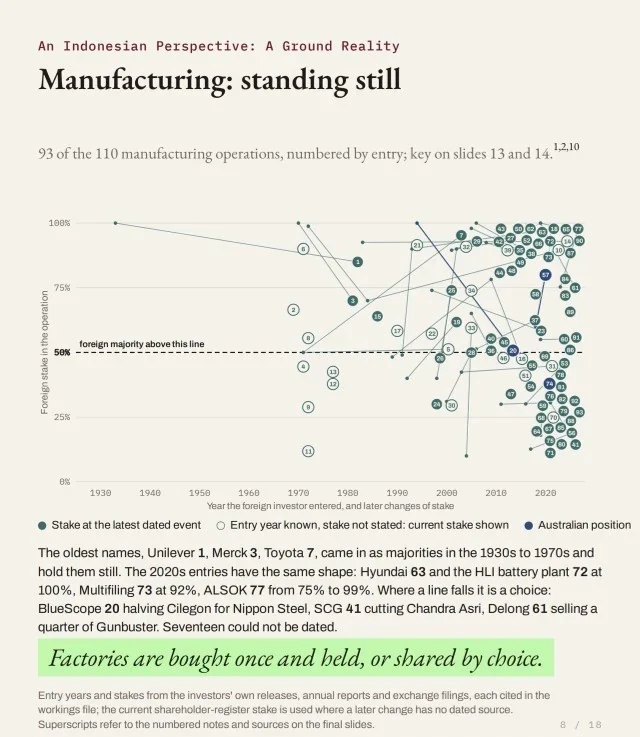
- Factories are bought once and held. Unilever, Merck and Toyota came in as majorities decades ago and hold them still. Where a line falls it is a decision, not a rule: BlueScope halved Cilegon to bring in Nippon Steel.
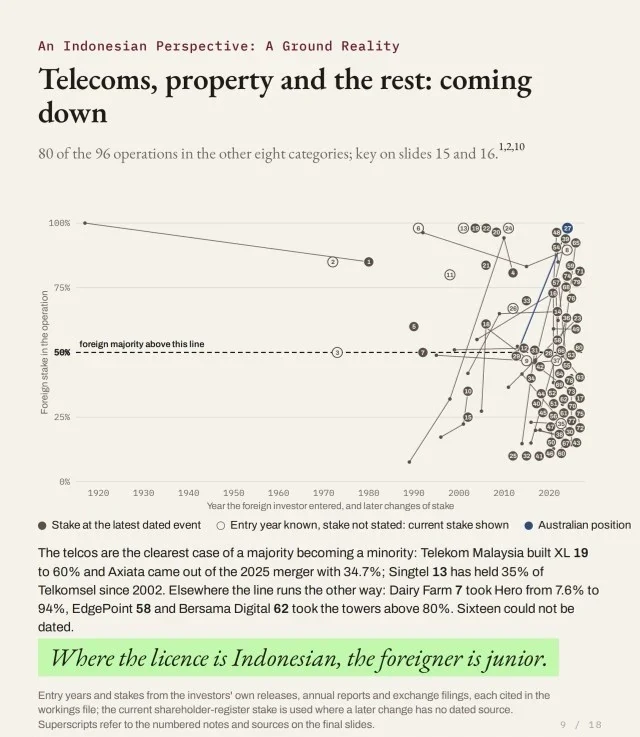
- Where the licence is Indonesian, the foreigner ends up junior. Telekom Malaysia built XL to 60% and came out of this year's merger with 34.7%. Singtel has held 35% of Telkomsel since 2002.
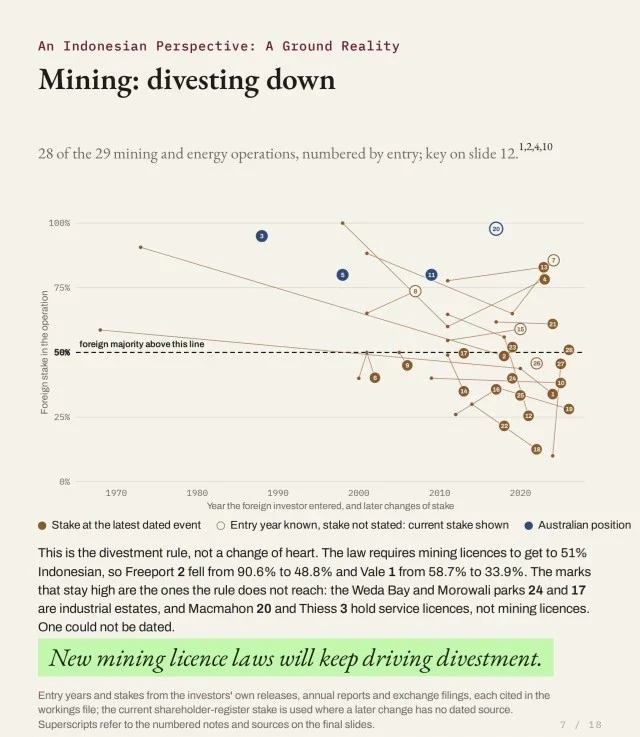
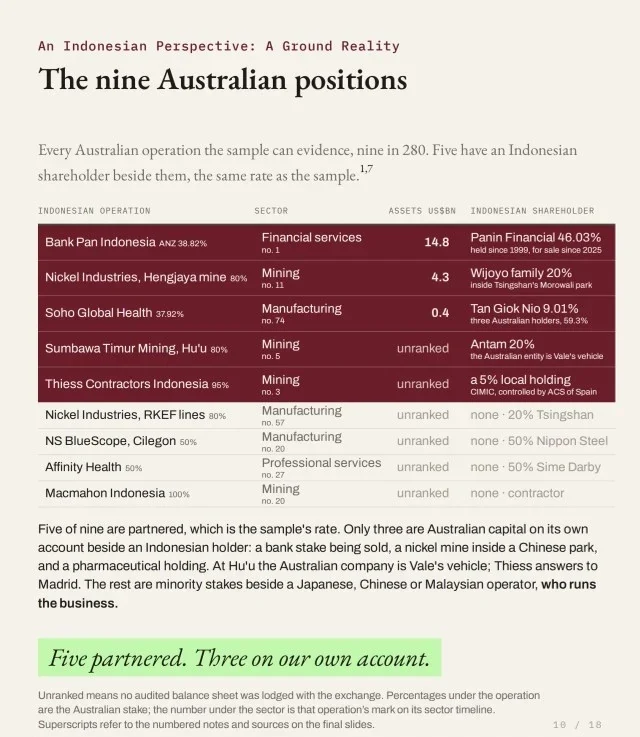
Australia has nine positions in the 280. Five sit beside an Indonesian shareholder, the same rate as the sample. But only three are Australian capital on its own account: a bank stake being sold, a nickel mine inside a Chinese park, and a pharmaceutical holding. At Hu'u the Australian entity is Vale's vehicle, and Thiess answers to Madrid. The rest are minority stakes beside a Japanese, Chinese or Malaysian operator, who runs the business.
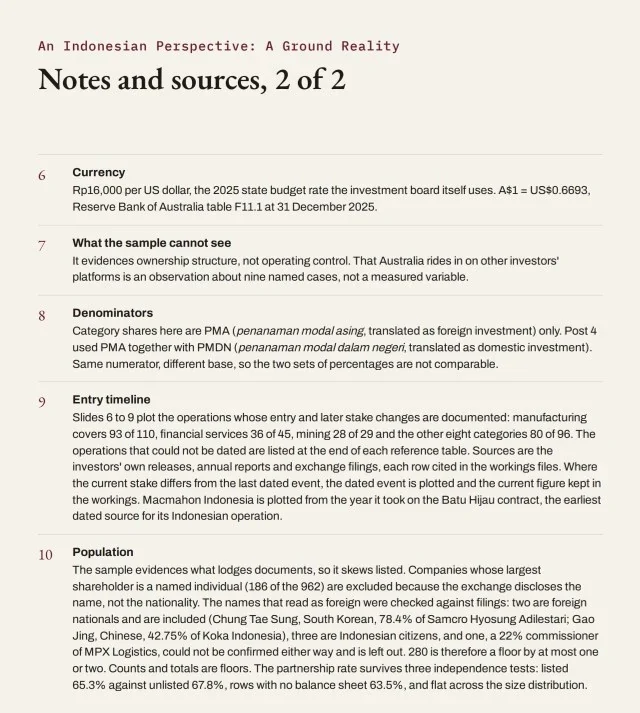
Two caveats. The sample evidences ownership structure, not operating control, and it skews listed, because those are the companies that lodge filings.
Key takeaways: Lack of foreign direct investment can't be blamed on the rules. Partnering with local businesses is evidently the dominant force.
Exhibits
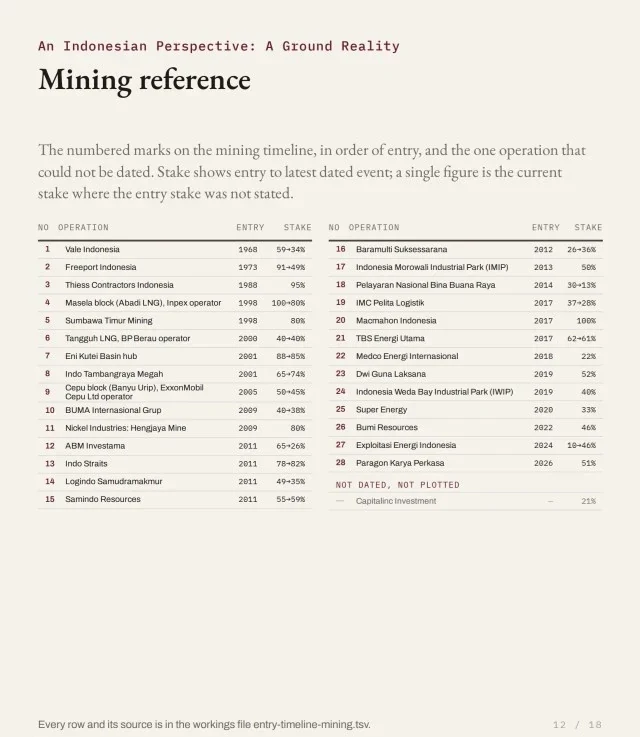
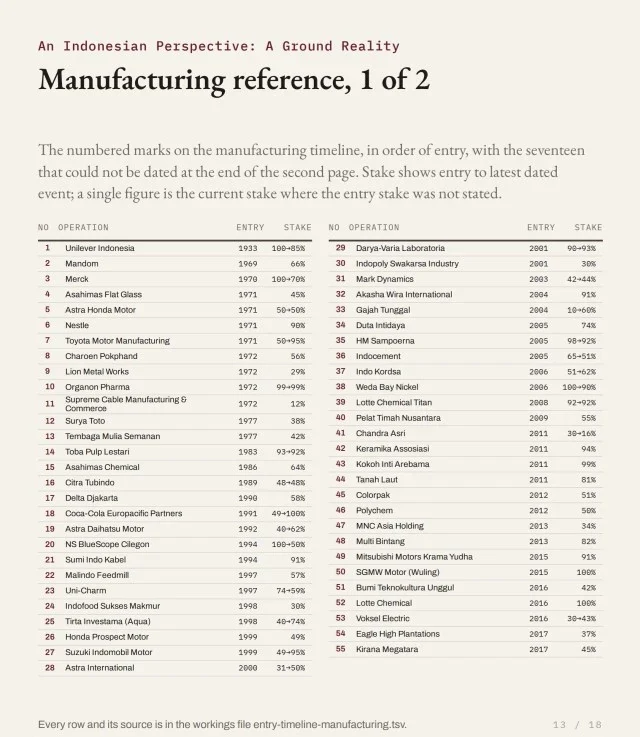
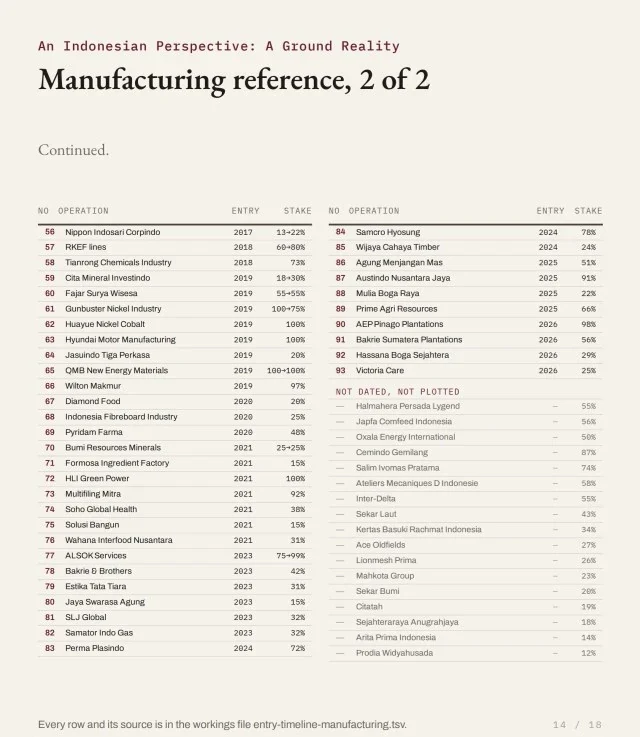
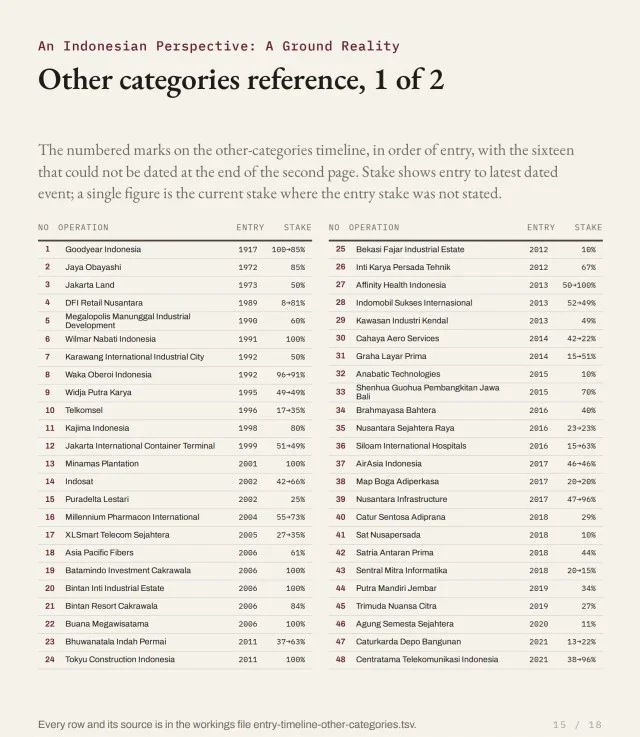
Swipe or use the arrows. Select an exhibit to open it full size.